
Understanding the Constant Product Formula: From Math to DeFi
You’ve probably heard traders talk about "slippage" or wonder why swapping a huge amount of tokens on Uniswap costs so much more than swapping a tiny amount. The answer isn’t just market volatility; it’s math. Specifically, it’s the Constant Product Formula, a mathematical relationship where the product of two variables remains constant (x * y = k). While this concept dates back to ancient Greek geometry, it is the engine running billions of dollars in today’s decentralized finance (DeFi) markets.
If you are trying to understand how automated market makers (AMMs) work, or if you’re a student struggling with inverse proportionality in physics class, this guide breaks down the formula without the academic jargon. We’ll look at what the formula actually means, how it powers crypto exchanges, and where it fails.
What Is the Constant Product Formula?
At its core, the Constant Product Formula is expressed as xy = k. Here, x and y are two variables that change inversely, and k is a fixed number that never changes.
Think of it like a seesaw. If one side goes up, the other must go down by an exact amount to keep the balance point (the product) steady. Unlike direct proportionality, where both variables move in the same direction (like distance and time when speed is constant), here they move in opposite directions. If x doubles, y must halve to keep k the same.
This isn’t just abstract theory. It appears everywhere:
- Physics: Boyle’s Law states that for a gas at constant temperature, Pressure × Volume = Constant (P·V = k). Squeeze the volume, pressure rises.
- Economics: In simple barter systems, if you have a fixed budget, buying more apples means you can buy fewer oranges.
- Crypto: Liquidity pools use this to price assets automatically.
The Graph: Why It Looks Like a Curve
If you plot xy = k on a graph, you don’t get a straight line. You get a rectangular hyperbola. This curve has two important features called asymptotes. As x gets huge, y gets close to zero but never touches it. As x gets close to zero, y shoots up toward infinity.
This shape matters because it explains why large trades impact prices so drastically. In a linear model, selling twice as many tokens might double your price impact. But in a constant product model, because of the curve’s steepness near the edges, selling a massive chunk of tokens can cause exponential price slippage. This is why whale trades often require splitting orders across multiple platforms-to stay on the flatter part of the curve where prices are stable.
How Uniswap Uses x * y = k
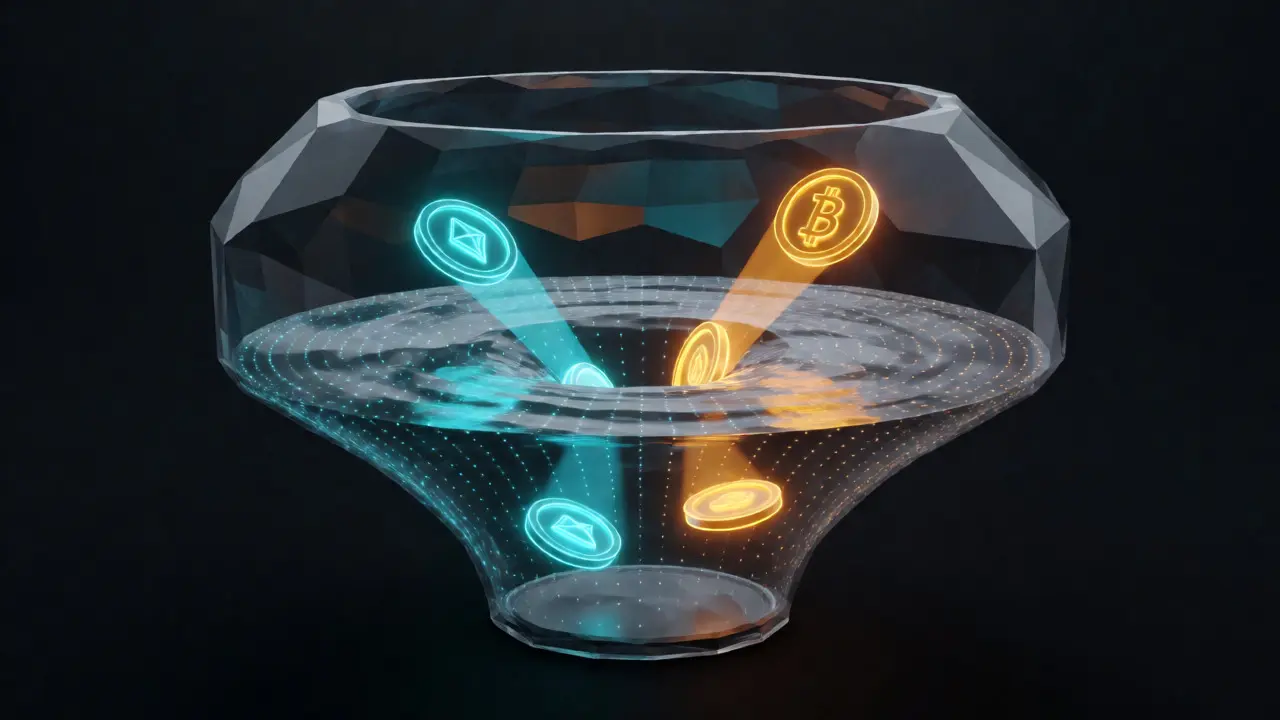
In traditional stock exchanges, buyers and sellers match via an order book. In Decentralized Exchanges (DEXs) like Uniswap, there is no order book. Instead, there is a Liquidity Pool, a smart contract holding reserves of two different tokens.
Let’s say you create a pool with ETH and USDC. Initially, the pool holds 100 ETH and 10,000 USDC. The constant k is 100 * 10,000 = 1,000,000.
- The Trade: You want to buy 10 ETH. You remove 10 ETH from the pool.
- The Constraint: The pool now has 90 ETH. To keep
kat 1,000,000, the new amount of USDC must be1,000,000 / 90 ≈ 11,111 USDC. - The Cost: Originally there were 10,000 USDC. Now there must be 11,111. So, you must deposit
1,111 USDCinto the pool.
Notice the effective price? You paid 1,111 USDC for 10 ETH, which is 111.1 USDC per ETH. Before the trade, the rate was 100 USDC per ETH. You paid a premium. That premium is the "price impact," and it exists solely because the formula forces the ratio to shift to maintain the constant product.
| Feature | Direct Proportionality (y = kx) | Constant Product (xy = k) |
|---|---|---|
| Relationship | Variables move in the same direction. | Variables move in opposite directions. |
| Graph Shape | Straight line through origin. | Rectangular hyperbola. |
| Example | Distance = Speed × Time (if speed is constant). | Price × Quantity = Total Value (in AMMs). |
| Impact of Large Change | Linear increase/decrease. | Exponential effect on the other variable. |
Why This Formula Matters for Crypto Traders
Understanding xy = k helps you predict costs before you click "swap." If you are trading small amounts relative to the pool size, the price impact is negligible. The curve is flat enough that the exchange rate barely moves. However, if you are trading large amounts, you are moving along the steep part of the hyperbola.
Here is a practical rule of thumb: Keep your trade size under 1% of the total liquidity pool value if you want minimal slippage. If you push it to 5-10%, expect significant deviation from the mid-market price. This isn't a bug; it's the feature that prevents arbitrageurs from draining the pool instantly during high volatility.
Furthermore, this formula creates incentives for Liquidity Providers (LPs). LPs earn fees from these trades. When the price of ETH rises against USDC, arbitrage bots will buy ETH from the pool until the ratio matches the external market. This rebalancing happens automatically because the formula forces the price to adjust whenever quantities change.
Limitations and Risks
The constant product model isn’t perfect. Its biggest flaw is Impermanent Loss. The difference between holding tokens versus providing them to a liquidity pool when prices diverge. Because the formula forces the pool to sell winners and buy losers as prices change, LPs often end up with less value than if they had just held the tokens in their wallets. This happens because the pool is constantly rebalancing based on xy = k, effectively selling assets as they rise and buying them as they fall.
Additionally, the formula assumes infinite divisibility and continuous trading. In reality, blockchain transactions happen in discrete blocks. During extreme market crashes, such as the TerraUSD collapse in 2022, the assumption that k remains stable breaks down because liquidity dries up faster than the formula can adjust, leading to severe slippage or failed transactions.
Learning the Math: Tips for Students
If you are learning this in school, the hardest part is distinguishing it from direct proportionality. A common mistake students make is setting up y = k/x incorrectly when solving word problems. Remember: if the problem says "as one increases, the other decreases," think product constant. If it says "as one increases, the other increases," think ratio constant.
Visual aids help. Draw the hyperbola. Mark points where x=1, y=10 and x=10, y=1. See how the area of the rectangle formed by the axes and the point is always 10? That area is k. Keeping this geometric visualization in mind makes algebraic manipulation much easier.
What does 'k' represent in the constant product formula?
In mathematics, 'k' is the constant of proportionality. In DeFi liquidity pools, 'k' represents the invariant product of the two token reserves. It ensures that the total value locked (roughly speaking) maintains a specific mathematical relationship, preventing the price from being manipulated easily without substantial capital.
Why do I pay higher prices for larger trades on Uniswap?
Because of the hyperbolic nature of the xy=k curve. Small trades occur on the flatter part of the curve where the marginal price change is low. Large trades consume more liquidity, pushing the reserves further apart and forcing the price to adjust exponentially to maintain the constant product 'k'. This results in higher average execution prices for the buyer.
Is the constant product formula used in traditional finance?
Not directly as a pricing mechanism like in AMMs. Traditional finance uses order books where buyers and sellers specify exact prices. However, the underlying math appears in economic models regarding supply and demand equilibrium, elasticity calculations, and certain derivative pricing models where inverse relationships between risk and return are modeled.
What is impermanent loss in relation to this formula?
Impermanent loss occurs because the xy=k formula forces the liquidity pool to rebalance. If the price of Token A rises significantly compared to Token B, the pool sells some Token A and buys more Token B to maintain k. If you had just held Token A, you would have more value. The loss is 'impermanent' because it disappears if the price returns to the starting point, but becomes permanent if you withdraw funds while the price is still diverged.
Can the constant product formula handle three tokens?
Yes, but the formula expands. For three tokens (A, B, C), the invariant becomes A * B * C = k. This is used in multi-token pools. The logic remains the same: the product of all reserve balances must remain constant after every trade, adjusting individual balances inversely to maintain the total product.
Ted Thoroughgood
September 10, 2026 AT 18:53Yo this is huge for beginners! I always got confused by slippage but seeing it as a seesaw makes total sense. Keep your trades small and you save money. Simple as that.
Sasha Wilde
September 11, 2026 AT 00:37It's not just "simple" it's fundamental 📉 The hyperbola isn't optional it's the law of AMMs. If you don't understand the asymptotes you're basically gambling blindfolded. Most people lose money because they ignore the math. 🧠💸
Saket Kulkarni
September 12, 2026 AT 23:34I appreciate the clarity in this exposition. It is fascinating how ancient geometric principles govern modern financial instruments. The parallel to Boyle's Law is particularly apt for those of us with scientific backgrounds. We must respect the immutable nature of k.
Eliza Stein-Dodd
September 14, 2026 AT 17:23Exactly right! 🎯 And don't forget impermanent loss. That's the hidden tax on LPs. xy=k forces you to sell winners and buy losers. Ouch. 😬
Kathy Siew
September 15, 2026 AT 17:56Oh great another explainer that ignores the fact that gas fees eat your lunch anyway. Sure the math works if you have infinite money for ETH gas. For the rest of us peasants its just expensive roulette. But hey nice graph.
Brittany Ross
September 17, 2026 AT 13:03This actually helped me so much! I was staring at my portfolio crying about IL yesterday and this made me feel like maybe I didn't totally mess up? 😭🙏 The visualization of the rectangle area being constant is such a good trick for remembering it.
Maegan Rust
September 19, 2026 AT 07:19The curve... oh, the beautiful, cruel curve. It whispers promises of liquidity but screams warnings of slippage. To trade is to dance with the hyperbola, where every step forward costs exponentially more than the last. We are but fleeting reserves in the eternal pool of k.
Harish Ramaiah
September 19, 2026 AT 19:40Mostly swap pools like Uniswap V2. Lido uses different mechanisms for rebasing tokens. Stick to the AMM context here.
Jennifer Brosnan
September 21, 2026 AT 18:36Correct. The invariant holds for the reserves of the two assets in the liquidity pool specifically. Staking derivatives operate on supply/demand dynamics rather than a strict x*y=k constraint in the same way.
Idowu Emmanuel
September 23, 2026 AT 16:48Nice breakdown. One thing missing though: what happens when k changes? Like when someone adds or removes liquidity? Does the curve shift instantly? Because that seems like a major source of confusion for newbies who think price impact is only from trading volume.
Finlay Samms
September 24, 2026 AT 00:13Good point mate. When liquidity is added k increases which effectively flattens the curve reducing slippage for future trades. Removing liquidity decreases k making the curve steeper. So yes the curve shifts dynamically based on TVL. Its all connected. :)
lea terrade
September 25, 2026 AT 03:42i keep thinking about how this mirrors life. we try to keep balance (k) but every action has an equal opposite reaction. if i gain time i lose energy. if i gain money i lose freedom. the constant product of existence. heavy stuff. 🤔
Rachel Leet
September 27, 2026 AT 01:11While poetic, this analogy breaks down under scrutiny. Human choices aren't constrained by a fixed invariant in the same mechanical way atomic swaps are. You can create value ex nihilo through labor; you cannot create ETH out of thin air in a closed pool without external input. Don't confuse metaphor with mechanism.
John Lewis
September 27, 2026 AT 18:46Agreed with the previous commenter. The formula assumes a closed system. Real markets are open systems influenced by news sentiment regulation etc. The math is a model not reality.
Sophie Fitzgerald
September 28, 2026 AT 10:41Short and sweet: Large trade = High slippage. Small trade = Low slippage. That's the whole article condensed.
Ritchie Grogg
September 28, 2026 AT 16:26Thanks for sharing this. As someone who teaches high school physics I'm definitely using the Boyle's Law comparison next week. It bridges the gap between their science class and their crypto obsession perfectly. Much appreciated!
Alexander James
September 29, 2026 AT 03:34Also worth noting that Uniswap V3 changed things slightly with concentrated liquidity ranges but the core inverse relationship remains within each tick range. Still relevant.